



Things you might not know about your nest egg
Savers hold almost $15 trillion in workplace retirement plans and IRAs, according to data recently released by the Investment Company Institute.
That may seem like a lot of cash to manage, but relatively few Americans apparently have tried to figure out if it is enough to get them through retirement.
Just 41 percent of workers have tried to assess how much money they’ll need in retirement, and only 1 in 10 have created a formal, written plan, according to the 2017 Retirement Confidence Survey from the Employee Benefit Research Institute, conducted by research firm Greenwald & Associates.
Think you know all you need to about retirement accounts? Here are some things that might catch you by surprise:
– No one agrees how you should invest. While competing target-date mutual funds (portfolios that gradually grow more conservative as retirement approaches) have generally become more in tune with each other over the past few years, some experts say there’s good reason to customize these one-stop retirement savings vehicles.
Workers for a national retailer with a lot of company stock in the 401(k) plan might have a very different risk profile than physicians in a large medical practice, for example. Companies can now customize their target-date 401(k) plans to their workforces, Tom Idzorek, head of investment methodology for Morningstar Investment Management LLC, recently told a Pensions & Investments industry forum.
Your own company might not be looking at this yet, but it’s smart to be aware of how your target-date fund changes its allocation to stocks and bonds over time.
– Creating a paycheck is harder than it seems. For all the talk about employers helping workers turn those 401(k) plans into steady streams of income in retirement, most plans still aren’t set up to distribute income to retirees on a regular basis. That means retirees are forced to roll their money into an IRA when they are ready to begin distributions, even if they wanted to leave the money in a workplace plan because it offers lower fees or better service than they could find in the retail IRA market.
– HSAs are the new IRAs. Health savings accounts are increasingly viewed by financial experts as excellent long-term savings accounts because of their triple tax advantages. Contributions are made on a pre-tax basis, they grow tax-free and withdrawals are tax-free if used to pay for health care.
– Rising rates to the rescue. With the Federal Reserve finally beginning to hike interest rates, retirees could start to see some increased yield on certificates of deposit and other fixed-income assets. Because the increase is expected to be mild, however, that shouldn’t be the death knell for stocks, said Bob Miller, portfolio manager of the BlackRock Total Return Fund. That suggests retirement investors should stick to a balance of stocks and bonds that best fits their time horizon, experts say.
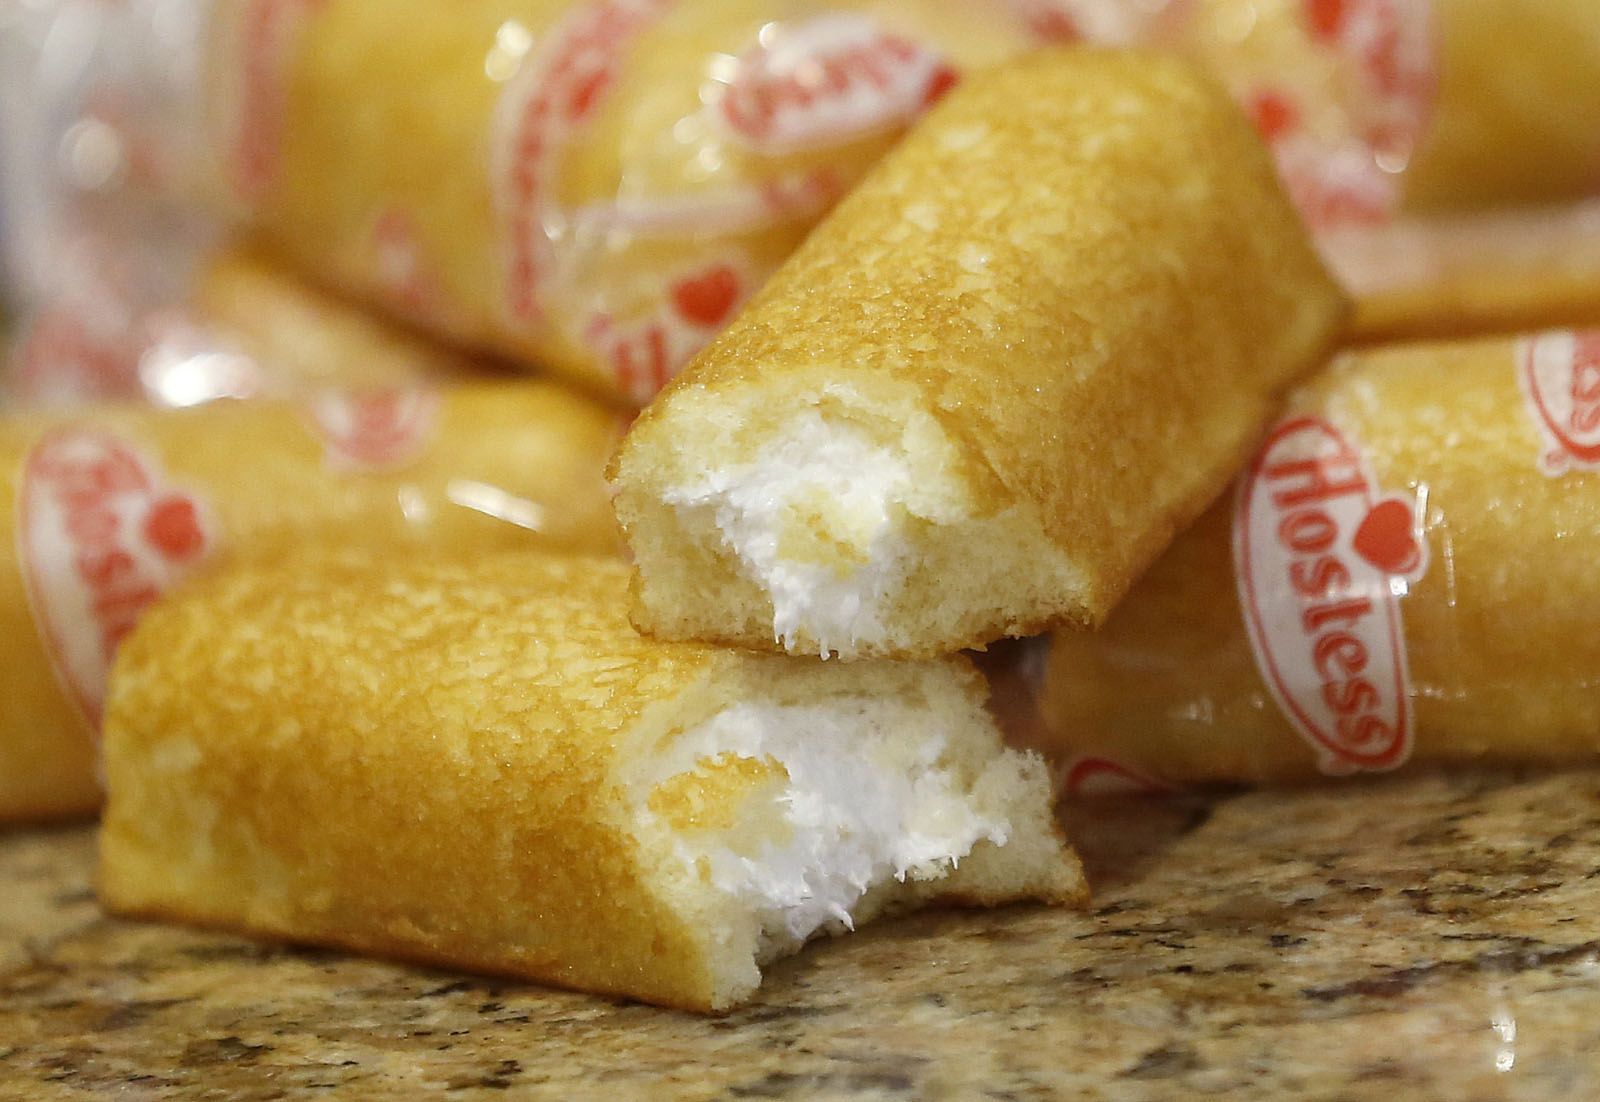
FILE – In this Monday, July 15, 2013 file photo, Twinkies are displayed in Gilbert, Ariz. A southwestern Missouri woman is sending Hostess snack cakes to troops in Afghanistan as part of a campaign called Operation Twinkie. Trisha Monroe told The Joplin Globe that 384 boxes of the treats were delivered to her Oronogo home Monday. She said she’ll begin sending the Hostess cupcakes and Twinkies this weekend to soldiers overseas. (AP Photo/Matt York, File)
FILE – In this Monday, July 15, 2013 file photo, Twinkies are displayed in Gilbert, Ariz. A southwestern Missouri woman is sending Hostess snack cakes to troops in Afghanistan as part of a campaign called Operation Twinkie. Trisha Monroe told The Joplin Globe that 384 boxes of the treats were delivered to her Oronogo home Monday. She said she’ll begin sending the Hostess cupcakes and Twinkies this weekend to soldiers overseas. (AP Photo/Matt York, File)